



Senegal’s bonds are trading at half their face value. Its president just flew to Washington anyway, smiling for the cameras with the woman who once suspended his country’s lifeline.
That contradiction, distress in the markets next to warmth in the meeting room, is the real story behind this week’s headlines about a new Senegal IMF programme. Behind the handshakes, a Senegal IMF programme worth 2.2 billion dollars still hangs on approvals nobody can promise.
On Tuesday, President Bassirou Diomaye Faye sat down with IMF Managing Director Kristalina Georgieva at Fund headquarters. Afterwards, both sides spoke of progress and partnership.
Georgieva said Senegal had made encouraging strides in strengthening its economy and improving prospects for jobs and investment. The Senegalese presidency, in a statement on X, said the pair had pledged to move quickly towards a new programme.
It sounded simple. A Senegal IMF programme rarely is.
To understand why this meeting mattered, you have to go back two years.
In 2024, Faye’s newly elected government accused the previous administration of Macky Sall of hiding the true state of the country’s finances. What they found was staggering.
The 2023 budget deficit, officially reported at 4.9 percent of GDP, was actually 12.3 percent. More than 11 billion dollars in extra debt had gone undisclosed. Some analysts put the true figure closer to 13 billion dollars, more than a quarter of everything Senegal owed.
The IMF’s response was swift. It suspended a 1.8 billion dollar programme agreed in 2023 and sent staff back to Dakar to work out what had really happened.
What followed was a long, patient rebuilding of trust.
A mission in June looked at the fallout from the war in the Middle East on Senegal’s finances. A July visit by the Fund’s new Africa department head, Zeine Zidane, included meetings with President Faye and Prime Minister Ousmane Sonko to keep talks alive.
Each visit inched the two sides closer to a Senegal IMF programme, without quite arriving.
The breakthrough came on 1 September, when an IMF team led by Mercedes Vera Martin wrapped up nearly two weeks of talks in Dakar.
The result was a staff-level agreement on a new Senegal IMF programme worth roughly 2.2 billion dollars, running for 36 months under the Extended Credit Facility. It is intended to support Senegal’s economic reform plans through 2029, covering everything from public debt management to social spending.
Here is the tension.
A Senegal IMF programme built on a staff-level agreement is not a done deal. It still requires approval from IMF management and the Executive Board, and no board date has been announced.
Senegal must first secure what the Fund calls a waiver, allowing the IMF to proceed despite the earlier debt-misreporting case. It must also demonstrate that it has financing assurances from its partners, a diplomatic way of saying creditors need to agree on how they will eventually be repaid.
That is where the debt treatment plan comes in.
On the same day as the staff-level agreement, Senegal’s finance ministry asked the G20 to apply its Common Framework, the mechanism designed for sovereign debt restructuring, to roughly 5 billion dollars of Eurobonds and other foreign-currency commercial debt.
Officials want a faster timetable than the Common Framework usually allows, with creditor negotiations running in parallel rather than one lengthy stage after another.
Markets are not waiting for niceties.
Senegal’s bonds have fallen to record lows, all trading below 50 cents on the dollar or euro. That is half their original value, a blunt verdict from investors who doubt they will be repaid in full and on time.
Contrast that with the language coming out of Washington this week, all warmth and momentum, and the gap between diplomacy and pricing becomes hard to ignore.
There is a domestic complication too.
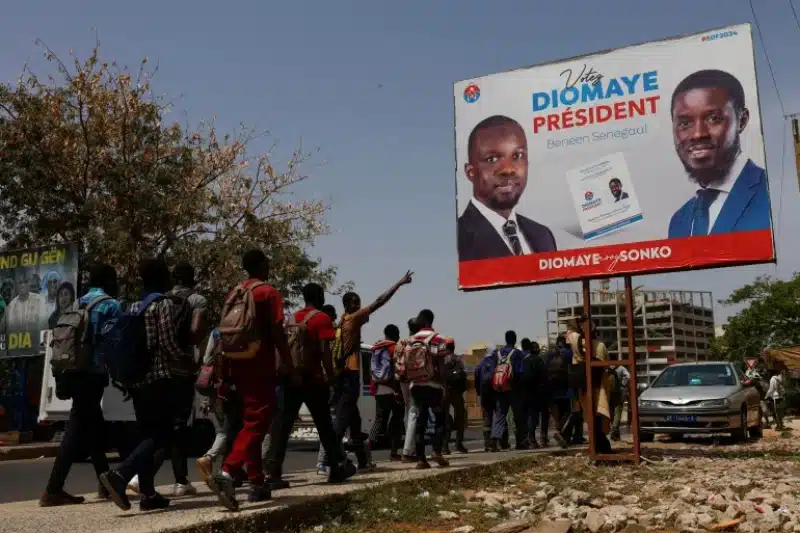
Faye removed Ousmane Sonko as prime minister in May. Sonko was soon appointed president of the National Assembly, a position that gives him significant influence over legislation, including reforms tied to a future Senegal IMF programme.
Whether he uses that platform to support the government’s fiscal turnaround or slow it down remains one of the quieter questions hanging over Dakar.
Still, there are genuine bright spots.
Senegal’s economy grew by 6.7 percent in 2025, its first full year of oil production, even as growth outside hydrocarbons slowed to 2.2 percent.
The overall fiscal deficit narrowed sharply, from 13.4 percent of GDP in 2024 to 6.4 percent in 2025, largely through spending cuts rather than fresh borrowing.
Total public debt is reported at around 132 percent of GDP, among the highest levels in sub-Saharan Africa, though the broader trend has improved. This figure should be verified against the latest IMF and government data before publication if not already sourced directly.
The IMF has said a finalised Senegal IMF programme could help unlock additional financing from institutions such as the World Bank and the African Development Bank, widening the pool of support beyond the Fund itself.
That is the incentive pulling Dakar towards compliance.
The risk is that corrective measures required by the waiver process collide with political realities in parliament, where Sonko now holds considerable influence. Another possibility is that creditors resist the accelerated Common Framework timetable Senegal is seeking, leaving the Senegal IMF programme stalled despite recent progress.
None of that was resolved on Tuesday.
What Faye and Georgieva produced was a photograph and a pledge towards a Senegal IMF programme, not a signed cheque.
The Executive Board still has to meet. The waiver still has to be granted. The bondholders still have to agree.
But after a scandal that erased trust almost overnight, arriving at the negotiating table smiling is, for Senegal, already a form of progress.
The real test will not be in Washington.
It will be whether a country that once hid a quarter of its debt can now convince the people it owes money to that the numbers, finally, can be believed.


